Auto Insurance
See If You're Paying Too Much for Auto Insurance
Already have car insurance? That's fine. I'll compare what you're currently paying and the coverage you have against options from multiple insurance companies. If there's a better fit, I'll show you. If what you already have makes more sense, I'll tell you that too.
Based in Camp Hill • Serving Perry, Cumberland & Dauphin Counties
When Does It Make Sense to Shop Your Auto Insurance?
Insurance pricing changes over time — a carrier that was competitive for you a few years ago isn't necessarily still the best option. It's worth checking if:
- —Your renewal premium just increased.
- —You haven't compared rates in a few years.
- —You bought another vehicle.
- —You're adding a driver.
- —You're moving.
- —You're buying a home and may benefit from bundling.
- —Your household has changed.
- —You're simply wondering whether you're still getting a competitive rate.
None of that guarantees switching will save you money. It just means it's worth a look.
A Cheaper Quote Isn't Better If the Coverage Is Worse
If I find a quote that's cheaper because it strips away coverage you actually need, that's not much of a deal. I compare the numbers alongside the coverage so you can see what you're actually getting — things like:
- —Liability limits
- —Comprehensive & collision deductibles
- —Uninsured/underinsured motorist coverage
- —Rental reimbursement
- —Roadside assistance
- —Full tort vs. limited tort
- —Coverage for additional vehicles/drivers
Shopping Your Auto Insurance Doesn't Have to Be Complicated
Tell Me What You Have
Send your current policy information or give me the basic details I need.
I'll Compare Your Options
I'll look at available options from the carriers I work with and compare price and coverage.
You Decide
I'll explain what I found. Switch if it makes sense, or keep what you have.
"I'm Pretty Happy With My Current Insurance."
That's completely fine. Shopping your insurance doesn't mean you have to leave your current company — it just gives you something to compare it against.
“I don’t know what coverage I have.”
That's normal. Send me your current declarations page and I'll walk through what you're actually covered for.
“I don’t want to lose coverage just to save money.”
Agreed — that's why I compare coverage, not just the premium number.
“Switching sounds like a hassle.”
I handle the parts that are usually the hassle. You review and decide.
“What if you can't beat my current price?”
Then I tell you that, and you keep what you have.
Already Have a Good Deal? I'll Tell You.
I'm not going to tell you to switch insurance just so I can write a policy. If your current option looks better, I'll tell you. The point of getting a quote is to find out.
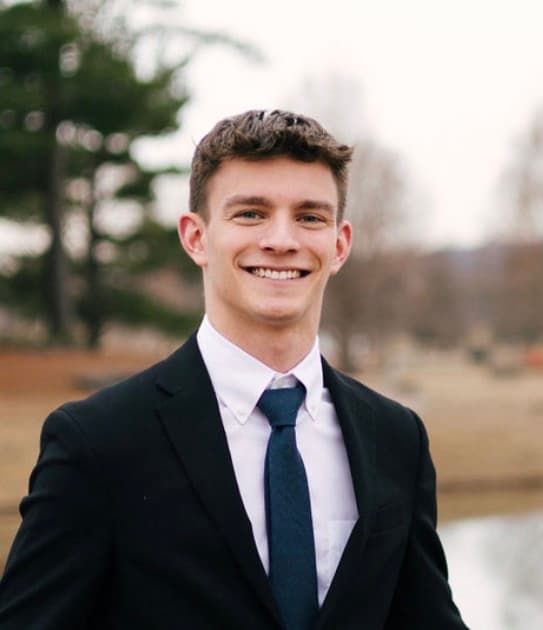
I'm Dawson Engle, an independent insurance agent based in Camp Hill. I work with multiple carriers so the comparison is actually a comparison — not a pitch for one company's product.
Auto Insurance FAQ
How often should I shop my auto insurance?+
There's no fixed rule, but it's worth checking anytime your premium jumps at renewal, your household changes, or it's just been a couple years since you last compared. Rates move over time even if nothing about you has changed.
Can you bundle my home and auto insurance?+
Often, yes — I can look at both together and see whether bundling with one carrier makes sense for your overall cost and coverage. Sometimes it does, sometimes keeping them separate works out better. I'll tell you which.
What information do you need to quote my car insurance?+
Your current policy or declarations page is the fastest starting point. If you don't have it handy, I can work from your vehicle info, drivers on the policy, and your current coverage limits.
Do I have to cancel my current policy before getting a quote?+
No. Getting a quote doesn't commit you to anything. If you decide to switch, I'll help you time the change so there's no gap in coverage.
Can you help me understand my current coverage?+
Yes — that's usually the first thing we go through. A lot of people aren't totally sure what their limits and deductibles actually mean until someone walks through it with them.
What is full tort vs. limited tort in Pennsylvania?+
It's a Pennsylvania-specific choice that affects your right to sue for pain and suffering after an accident. Full tort preserves that right; limited tort restricts it in exchange for a lower premium. It's worth understanding which one you have — I can explain what your current policy says.
Do you insure young drivers?+
Yes. Adding a teen or young driver to a policy is one of the more common reasons people reach out — I can walk through the options for your situation.
Can you insure multiple vehicles?+
Yes, multi-vehicle households are routine. I'll quote the whole household together so you can see the full picture.